

African stock markets are no longer passive recipients of global financial shocks. They have emerged as distinctive investment destinations capable of delivering world-class returns even in the most challenging geopolitical environments, according to James Norris, Corporate Africa Financial Analyst,
The third quarter of 2026 has proven to be a watershed period for African stock markets, defying global geopolitical turbulence to deliver some of the strongest equity returns worldwide. While wars in Ukraine and the Middle East have reshaped global risk perceptions and triggered capital reallocation, African exchanges have demonstrated remarkable resilience, driven by macroeconomic reforms, currency stabilization, and robust domestic investor participation.
Africa Outperforming Global Peers
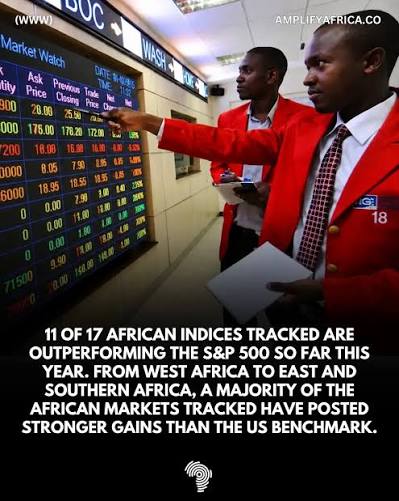
African stock markets entered Q3 2026 on exceptionally strong footing. The Nigerian Exchange (NGX) All-Share Index had posted a year-to-date return of nearly 60 per cent by July, with market capitalization closing in on N160 trillion. By August 31, Nigeria had reclaimed its position as Africa’s best-performing stock market, delivering a 69.5 per cent return in US dollar terms year-to-date—the highest among 17 African exchanges tracked. This performance placed Nigeria second globally in Bloomberg’s ranking of 92 stock markets worldwide.
However, the rankings have been fiercely contested. Zimbabwe overtook Nigeria in late July with a 67.4 per cent dollar return, while Ghana ranked third at 59.8 per cent. By early August, Zimbabwe had emerged as Africa’s best-performing market with a 71 per cent YTD dollar return, followed by Nigeria at 68.2 per cent and Ghana at 63.5 per cent. South Africa’s JSE, in contrast, remained relatively flat, highlighting the divergence between frontier and more developed African markets.
The West African regional exchange, BRVM, also reached historic heights, surpassing 20,036 billion FCFA in market capitalization. Kenya’s Nairobi Securities Exchange (NSE) saw its market capitalization surge 41.56 per cent since January, reaching a record 4,170 billion Kenyan shillings (US$32.3 billion).
The Top 10 Winning Markets
Based on comprehensive data from African Markets and Bloomberg tracking, the top-performing African stock markets in Q3 2026 (YTD dollar returns as of August/September) were:
1. Nigeria (NGX) – 69.5 per cent
2. Zimbabwe (ZSE) – 67.4 per cent
3. Ghana (GSE) – 59.8 per cent
4. Tunisia – approximately 46-48 per cent
5. Tanzania (DSE) – approximately 40-44 per cent
6. BRVM (West Africa) – 53.88 per cent
7. Kenya (NSE) – 28-33 per cent
8. Egypt (EGX) – approximately 21.7 per cent
9. Zambia – approximately 19.5 per cent
10. Uganda – approximately 18.1 per cent
Top Performing Sectors and Companies
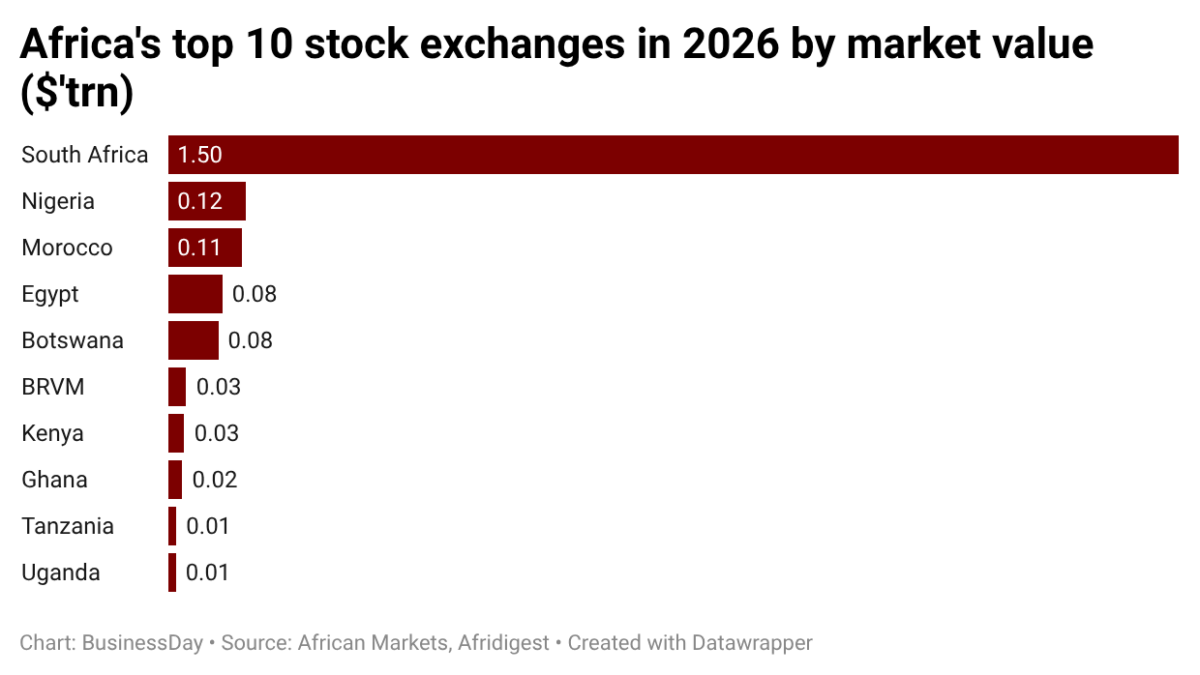
Banking emerged as the dominant winning sector across virtually all African exchanges. In Nigeria, banking stocks topped every major research house’s Q3 picks, underpinned by recapitalization gains, earnings resilience, and dividend potential. The banking sector’s strength was driven by high interest rates boosting margins and improved asset quality. In Kenya, the banking index surged 40.12 per cent since the beginning of 2026, outperforming all other NSE indices.
Telecommunications ranked as the second most influential sector. On the BRVM, telecoms represented 33.36 per cent of total market capitalization. Maroc Telecom delivered a 28.1 per cent ROE, while Airtel Africa reported record earnings with revenue rising 29.5 per cent to US$6.42 billion year-on-year. Airtel Africa was among the best-performing African stocks globally with a total return of 85.25 per cent.
Industrial goods and cement also performed strongly, with Dangote Cement (US$9.9bn market cap) and BUA Cement ($8bn) leading Nigeria’s industrial sector.
Insurance showed remarkable returns, particularly in West Africa, where AFMA delivered a 102.1 per cent ROE.
Individual standout companies included:
· Africa Energy (HPMCF) – 85.25 per cent total return
· Car & General (Kenya) – 359.31 per cent YTD gain despite a late correction
· Safaricom (Kenya) – reached highest level since February 2022, representing over one-third of NSE’s total capitalization
· Kenya Airways – +76.20 per cent
· Zichis Agro Allied Industries (Nigeria) – 365.49 per cent YTD gain
· Seplat Energy (Nigeria) – key contributor to Africa ex-SA Fund performance
Investment Flows: Highs and Lows
FDI Resilience and Gulf Sovereign Wealth
Despite geopolitical headwinds, foreign direct investment (FDI) into Africa demonstrated remarkable resilience. FDI inflows rose 75 per cent year-on-year to reach $97 billion. Egypt led with approximately $46.58 billion in FDI, followed by Ethiopia (US$3.98 billion), Côte d’Ivoire (US$3.8 billion), and Mozambique (US$3.55 billion). Nigeria recorded a rebound in Q3 FDI, attracting approximately US$720 million in capital inflows. Tanzania doubled its FDI inflows to over US$1.05 billion in Q3.
Gulf sovereign wealth funds emerged as transformative investors, deploying over US$1.2 billion into pan-African payment gateways in the first half of 2026 alone. UAE and Saudi Arabian funds aggressively diversified into African telecommunications, viewing Sub-Saharan Africa as “the world’s primary growth frontier for digital infrastructure and renewable energy”. Between 2012 and 2025, Gulf states invested approximately US$179 billion across Africa, and by 2026, more than US$101.9 billion had flowed into Africa’s renewable energy sector from Gulf countries.
Portfolio Outflows and Capital Flight
However, portfolio investment flows told a different story. The Nairobi Securities Exchange suffered Sh8.8 billion (US$68 million) net foreign investor outflows in Q3 (January-March 2026), a 90 per cent jump from the previous quarter. Foreign investor participation in Kenya’s equities market declined by 10 per cent. The capital flight was directly attributed to “prevailing geopolitical tensions in the Middle East region, which prompted global investors to rebalance their portfolios in favor of safer investment destinations”.
The five largest firms on the Nairobi bourse lost Sh200 billion in valuation since the start of the US-Israel war with Iran. Foreigners sold a net Sh4.05 billion worth of shares at the NSE following the Iran conflict. This created “dual pressure on both the equity market and the national currency”.
South Africa’s JSE also suffered, with the FTSE/JSE All Share remaining approximately flat to negative, as the Iran war “dealt a heavy blow to early optimism”.
Currency Dynamics and the Dollar Effect
Currency movements emerged as perhaps the single most critical factor shaping African equity returns in 2026. The Nigerian naira appreciated roughly 4 per cent against the dollar in 2026, following a 5.9 per cent appreciation in 2025. This currency strength meant that the NGX’s dollar return (approximately 67 per cent) actually exceeded its naira return. As analysts noted, “the value of the dollar is weakening while African currencies are stabilizing or rallying, a considerable turnaround following years of FX losses”. The naira was ranked the world’s second-best performing currency in 2026.
This represented a dramatic reversal from historical patterns. Research indicates that “a depreciation of the exchange rate crashes the valuation of the stock market”. Conversely, currency appreciation amplifies returns for foreign investors. Both Nigeria and Egypt entered the crisis period with “stronger macroeconomic foundations,” implementing more orthodox policies including tighter monetary policy, positive real interest rates, and more market-determined exchange rates.
However, not all currencies fared well. The Africa Confidential report noted that “weaker domestic currencies and a stronger dollar, at a time of increased investor risk aversion, could undermine debt-servicing capacity in several African states”. Twenty-nine African currencies depreciated following the Iran war. The Egyptian pound weakened from below EGP48 per dollar pre-conflict to nearly EGP55 at the height of market pressure before recovering.
The Impact of the Ukraine War
The Russia-Ukraine war, now in its fourth year, continued to exert significant influence on African markets throughout Q3 2026. The conflict acted as a “stress test” for African financial markets, “revealing their increased exposure to global shocks and a persistent underestimation of extreme risks”.
The outbreak of conflict in early 2026 “triggered a sharp risk-off episode, with the EFM Africa ex-SA Index declining 13.3 per cent to a trough on 31 March 2026”. Energy and food prices spiked, creating inflationary pressures across the continent. African markets experienced “significantly more acute and disorderly price movements than in normal periods”.
The war highlighted structural vulnerabilities: dependence on commodities, indirect exposure to global financial flows, and the narrowness of the domestic investor base. African financial markets, “although weakly integrated in the strict sense with major international financial centers, are no longer protected from global shocks”.
However, African economies entered this crisis from a stronger position than in 2022, having “implemented more orthodox and market-friendly policies in recent years”. Policymakers responded “in a more proactive and disciplined manner” and “seemingly avoiding the types of distortive measures implemented in previous crises, such as the imposition of capital controls”.
The Impact of the Iran-USA-Israeli War
The US-Israel strikes on Iran, launched on February 28, 2026, triggered a cascade of economic consequences across Africa. The IMF downgraded Sub-Saharan Africa’s growth forecast to 4.3 per cent in 2026, a 0.3 percentage point reduction from pre-war projections. North Africa’s growth forecast was slashed from 3.9 per cent to 1.1 per cent.
The most immediate impact was on energy prices. Oil broke $100 per barrel—roughly 50 per cent above February levels—with predictions of over $120 if the Strait of Hormuz closure persisted. A $20 rise in oil prices alone could drag Congo-Kinshasa’s current account down by more than 3 per cent of GDP, and those of Ethiopia, Kenya, Uganda, and Tanzania by close to 1 per cent each.
Fuel shortages worsened in Kenya, South Africa, Nigeria, Ethiopia, and multiple other countries. Fertilizer shortages threatened harvests, and reduced remittances from the Middle East squeezed household incomes across East Africa. The cessation of gas flows through Israel’s pipeline coincided with threats to Suez Canal revenues and sliding tourism receipts in Egypt.
The Africa Union, UN Economic Commission for Africa, African Development Bank, and UNDP jointly warned that “the current tensions in the Middle East, continuously impacting key international transport routes, energy and fertilizer supply chains, will lead to a significant slowdown in African economic growth”.
Winners and Losers:
Winners in this environment included:
· Oil exporters (Nigeria, Angola) benefiting from higher crude prices, though gains were tempered by other disruptions
· Frontier markets with currency stability and reform momentum (Nigeria, Ghana, Zimbabwe)
· Banking sectors across the continent, benefiting from higher interest rate environments
· Telecommunications companies with resilient cash flows and dollar-denominated revenues
· Gulf sovereign wealth funds expanding their African footprints
Losers included:
· Oil-importing countries facing worsening trade balances, rising inflation, and constrained fiscal space
· Tourism-dependent economies (Rwanda, Seychelles, Egypt)
· Markets with high foreign portfolio exposure (Kenya, South Africa)
· Companies reliant on Middle Eastern remittances and supply chains
· Fertilizer-dependent agricultural sectors
Impact on Foreign Investment: A Tale of Two Flows
The wars have produced a paradoxical effect on foreign investment in Africa. On one hand, portfolio investment has suffered significant outflows as global investors de-risk. On the other hand, strategic FDI—particularly from Gulf states—has accelerated.
The conflict prompted “global investors to rebalance their portfolios in favor of safer investment destinations”. However, African markets demonstrated resilience through “the growing role of domestic investors in supporting market activity and sustaining liquidity”. Domestic participation “enhanced market stability and reduced vulnerability to abrupt capital reversals”.
Crucially, “at no point during the episode were investors unable to repatriate capital” from Nigeria or Egypt—a significant vote of confidence in policy reforms.
The wars have also reshaped investor risk perceptions. As one analysis noted, “Global conflicts from the Middle East to Ukraine are reshaping how investors assess risk—and challenging perceptions about Africa”. Some investors now view Africa as “a safer investment bet” amid global turmoil.
Conclusion
Q3 2026 has been a quarter of stark contrasts for African stock markets. The continent has delivered exceptional equity returns—with Nigeria, Zimbabwe, and Ghana leading global performance rankings—driven by currency stabilization, banking sector strength, and macroeconomic reforms. Yet these gains have been achieved against a backdrop of profound geopolitical turbulence.
The Ukraine war and the Iran-USA-Israeli conflict have imposed significant costs: slower growth forecasts, energy price shocks, currency pressures, and portfolio capital flight. The IMF’s downgrade of Sub-Saharan Africa’s growth to 4.3 per cent reflects the real economic toll. Twenty-nine African currencies have depreciated, and oil-importing nations face particularly severe challenges.
However, the resilience of African markets should not be underestimated. Domestic investors have filled the void left by fleeing foreign portfolio capital. Gulf sovereign wealth funds are pouring billions into the continent’s digital and renewable energy infrastructure. And crucially, major economies like Nigeria and Egypt have demonstrated that policy reforms—orthodox monetary policy, flexible exchange rates, and fiscal consolidation—can provide genuine protection against external shocks.
The message from Q3 2026 is clear: African stock markets are no longer passive recipients of global financial shocks. Through reform, resilience, and the growing strength of domestic capital, they are emerging as distinctive investment destinations capable of delivering world-class returns even in the most challenging geopolitical environments. The wars in Ukraine and the Middle East have tested this thesis severely—and so far, African markets have passed the test.
https://t.me/s/IZZI_officials
Xsmega caught my eye. Seems lottery-focused. I’m not a HUGE lottery guy, but always dream of hitting the big one, haha. Worth keeping an eye on for those mega jackpots! Check it out yourself: xsmega
I am very grateful for sharing this great testimonies with you, The best thing that has ever happened in my life is how I won the lottery. I am a woman who believes that one day I will win the lottery. Finally my dreams came through when I emailed Dr WEALTHY and told him I need the lottery numbers. I have come a long way spending money on tickets just to make sure I win. But I never knew that winning was so easy until the day I met the spell caster online which so many people have talked about that he is very great at casting lottery spells, so I decided to give it a try. I contacted this man and he did a spell and he gave me the winning lottery numbers. But believe me when the draws were out I was among winners. I won 2.100.000 Million Dollars. Dr WEALTHY truly you are the best, with this man you can win millions of money through lottery. I am so very happy to meet this man, I will forever be grateful to you. Email him for your own winning lottery numbers [ wealthylovespell@gmail.com OR WhatsApp +2348105150446
paypal casinos
References:
https://sportgalax.com/read-blog/2636_silver-oak-casino-im-test-pyo%D1%9F-spieler-erfahrungen-und-betrugstest-2025.html
harrah’s ak chin casino
References:
https://naijasingles.net/@lydableakley6
onyx blackjack
References:
https://motion-nation.com/read-blog/6827_die-8-besten-online-casinos-deutschlands-2025-im-vergleich.html
slot machine android
References:
https://dzmariage.com/@louanneastham
betboo casino
References:
https://git.malls.iformall.com/danelleswett97/500-casino-bonus-ohne-einzahlung1991/wiki/Casino-de-Monte-Carlo%3A-Der-komplette-Leitfaden
spotlight casino
References:
https://jobbridge4you.com/employer/liste-mit-neuen-casinos-2025/
indiana grand casino
References:
https://usetiny.link/delilahwomack9
casino queen st louis
References:
https://digitalsnax.com/ilagoodlet8293
europa casino
References:
https://etalent.zezobusiness.com/profile/dianamortlock
goldstrike casino
References:
https://www.ip-exhibitions.net/employer/das-ultimative-spielerlebnis-2024/
76xgame popped up on my radar. Decent games, not too shabby at all. If you’re bored, give it a try. Here’s the link: 76xgame
gulfport ms casinos
References:
https://short.vird.co/claudefrick838
3d roulette
References:
https://clcs.site/tiarabelt99693
deuces wild video poker
References:
https://url9xx.com/janessawolford
live casino maryland
References:
https://cambodiaexpertalliance.net/employer/south-point-spielbank-wikipedia/
lotus casino las vegas
References:
https://ehrsgroup.com/employer/online-casino-spiele-kostenlos/
valley view casino
References:
http://www.seoulschool.org/bbs/board.php?bo_table=free&wr_id=1492994
Für eure Wahl eures Anbieters, bei dem ihr mit echtem Geld spielen könnt, habe ich euch zahlreiche Tipps gegeben. Euch erwartet sicherer Spielspaß mit hervorragenden Slots und Tischspielen. Mein Test zeigt, dass euch die besten Internet Spielbanken Glücksspiele mit viel Unterhaltung, Boni und Sicherheit bieten. Ihr solltet euch vorab immer fragen, ob ihr bereit seid echtes Geld einzusetzen, um in einem Online Casino zu spielen. Bei Echtgeld Casinos spielen bei der Bewertung einer Willkommensprämie zahlreiche Faktoren eine Rolle. Ein attraktives Willkommenspaket mit Extraguthaben und Freispielen kann euch eure Online Casino Echtgeld Erfahrungen versüßen. Derzeit bietet kein Echtgeld Casino PayPal auf dem deutschen Markt an.
Sie gewährt Lizenzen an Betreiber, die ihre Dienste in Großbritannien und international anbieten möchten. Die MGA ist eine der bekanntesten und angesehensten Glücksspiellizenzen weltweit. Vor der Legalisierung des Glücksspiels war die Schleswig-Holstein-Lizenz die einzige deutsche Lizenz für Online-Casinos. Neben der Lizenzierung und Kontrolle von Glücksspielanbietern hat die GGL weitere wichtige Tätigkeitsbereiche.
References:
https://online-spielhallen.de/hitnspin-casino-test-bonus-bis-e800-spielen/
ameristar casino st charles mo
References:
https://usetiny.link/pamalaj1821354
21 black jack online subtitulada
References:
https://cz-link.click/meri153657140
Nachdem du dein Konto eröffnet und deine Kontaktdaten (E-Mail-Adresse und Telefonnummer) erfolgreich verifiziert hast, findest du die Freispiele in deinem Konto unter dem Bereich “Boni”. Dann haben wir eine fantastische Neuigkeit für dich, denn über unseren exklusiven Link bekommst du ganze 55 Freispiele ohne Einzahlung! Über unseren Link erhältst du als neuer Spieler sofort nach der Registrierung 55 Freispiele ohne Einzahlung und das völlig kostenlos und risikofrei. Registrierung, Einzahlung und Bonuscode eingeben. Falls du sowohl Freispiele als auch Bonusguthaben hast, beginne immer mit den 50 Free Spins.
Einige unserer Boni können nur im Zusammenhang mit einer festgelegten Mindesteinzahlung aktiviert werden. Nachdem wir Ihnen gezeigt haben, wie Sie die Promo Codes erhalten und aktivieren können, möchten wir Ihnen natürlich nicht die Vorteile, die für Sie durch die Nutzung der Bonus Codes entstehen können, vorenthalten. Befolgen Sie dafür einfach die folgenden Schritte und genießen Sie im Anschluss Ihr persönliches Abenteuer mit der erhaltenen Prämie!
References:
https://online-spielhallen.de/beste-online-casinos-deutschland-top-10-nov-2025-2/
silverstar casino spa
References:
https://lnkmob.com/XnaBzcpI
32red casino
References:
http://softwarescience.top:3000/abbysander413/8817201/wiki/Top+Online+Casinos+Deutschland+2025%253A+Liste+deutscher+Anbieter
silver slipper casino
References:
https://www.iqconsult.pro/employer/kostenlose-spielautomaten-online-und-andere-casino-spiele-demomodus/
nars casino
References:
http://www.thedreammate.com/home/bbs/board.php?bo_table=free&wr_id=5083392
titan casino mobile
References:
https://themass.media/read-blog/1182_lucky-ones-casino-erfahrungen-schweiz-2025.html
titan casino mobile
References:
https://clicabio.com/scarlettre
skykings casino
References:
https://skinforum.co.in/employer/bonus-1500-225-free-spins/
Die Lizenz von Curaçao, die nicht zu den strengsten der Branche zählt, bietet NV Casino dennoch einen gewissen Rahmen an Legalität. Diese können in Form von kostenlosen Spins oder einem Einzahlungsbonus vorliegen. Ja, viele Online-Casinos, einschließlich nv Casino, bieten besondere Willkommensboni für neue Spieler an. Klicken Sie darauf, um Anweisungen zur Wiederherstellung Ihres Passworts zu erhalten. Das nv Casino bietet zahlreiche Vorteile, die den Login-Prozess besonders lohnenswert machen. Egal, ob Sie ein erfahrener Spieler oder ein Neuling sind, der Zugang zu einer Vielzahl von Spielen, Boni und aufregenden Funktionen ist einfach und schnell. Das nv Casino Online Login bietet Spielern die Möglichkeit, in eine Welt voller Abenteuer und Nervenkitzel einzutauchen.
Mit der Vision gegründet, eine innovative und benutzerfreundliche Online-Glücksspielplattform zu schaffen. Freispiele müssen innerhalb von 7 Tagen nach Erhalt verwendet werden. Tischspiele tragen nur 10% zu den Umsatzbedingungen bei, während Slots 100% beitragen. Der Willkommensbonus hat Umsatzbedingungen von 35x dem Bonusbetrag, die innerhalb von 21 Tagen erfüllt werden müssen. VIP-Spieler erhalten prioritäre Bearbeitung mit verkürzten Auszahlungszeiten von 1-2 Stunden. “Unser VIP-Programm bietet nicht nur finanzielle Belohnungen, sondern auch persönliche Betreuung und exklusive Events für unsere wertvollsten Spieler.”
References:
https://online-spielhallen.de/beste-deutsche-online-casinos-mit-lizenz-nov-2025/
mail slot catcher
References:
https://bondlii.com/@emoryjankowski
casino luxeuil
References:
https://rentologist.com/profile/kimtallis28762
rapunzel video
References:
https://lifeskillsafrica.com/blog/index.php?entryid=94216
mcphillips street station casino
References:
https://url.pixelx.one/almanmu661857
Beliebt Glücksspielseiten haben Lizenzen mit einer Reihe von Softwareanbietern, so dass die Spieler mehr Auswahl haben. Unten sind die Hauptspielkategorien aufgeführt, die Sie im 2025 in den besten mobilen Casinos finden. Alle unser empfohlenen Casinos sind über alle Netzanbieter zugänglich, einschließlich Telekom, Vodafone, O2 und mehr. Unsere Listen enthalten einige der beliebtesten und größten Namen in der Glücksspielbranche und diese Seiten bieten Live-Spiele, Spielautomaten, Blackjack, Roulette, Poker, Videopoker, Bingo und mehr. Eine gute Website wird ständig neue Spiele hinzufügen und die renommiertesten Softwareanbieter verwenden. Spiele sind das, wofür sich die Leute anmelden, und das beste deutsche Online-Casino bietet eine große Auswahl an Spielen, aus denen die Spieler wählen können.
Kann man Echtgeld Spiele und Apps auf dem Handy spielen? Kann man auch mit Mobilgeräten um Echtgeld spielen? Bei einigen Kartenspielen wie Blackjack oder bei Video Poker Automaten sind die Auszahlquoten auch durch Strategien und eigenes Spielverhalten beeinflussbar. Diese Angebote reizen sehr und Sie haben sich deshalb schon im Internet mit einigen Casinoanbietern vertraut gemacht und Online Glücksspiele um Spielgeld ausprobiert. Die Gemeinsame Glücksspielbehörde der Länder (GGL) vergibt die offiziellen deutschen Lizenzen und führt gemäß § 9 Abs. Moderne Echtgeld Casinos ermöglichen es dir, deine Lieblingsspiele jederzeit und überall zu spielen – direkt auf deinem Smartphone oder Tablet. Aus Gründen des Spielerschutzes sind bestimmte, international beliebte Spielarten in deutschen Online Casinos derzeit nicht oder nur stark eingeschränkt verfügbar.
References:
https://online-spielhallen.de/400-casino-bonus-2025-beste-angebote-fur-deutschland/
nostalgia casino
References:
https://gtth.ghurkitrust.org.pk/employer/bonus-online-casino-2025-exklusive-casino-boni-in-deutschland/
Viele bieten ihren Casino Bonus automatisch oder über andere Aktivierungsmethoden an, dass kann unter anderem die Einzahlung oder ein Auswahlbutton sein. Es ist daher wichtig, die spezifischen Bonusbedingungen zu lesen, um zu verstehen, für welche Spiele der Casino Echtgeld Bonus mit Einzahlung gilt. Beispielsweise könnten Online Slots zu 100% beitragen, während Tisch- und Kartenspiele nur einen geringeren Prozentsatz oder sogar gar nicht zählen. Aber ich wünsche euch, dass das gelingt, ohne dass ihr Lehrgeld bezahlen müsst.
Nicht alle Online Casino Spiele bieten Dir kostenlose Casino Freispiele ohne Einzahlung für 2025 an. In den bekannten Online Casinos gibt es eine breite Auswahl an Bonusangeboten. Manche Casinoanbieter geben Ihnen anstelle von Guthaben auch einen No Deposit Freispielbonus. Freu dich auf spannende Spiele, höchste Sicherheit, schnelle Auszahlungen und attraktive Bonusangebote. Die meisten Online Casinos haben im Rahmen von verschiedenen Werbeaktionen oft ganz unterschiedliche Bonusangebote. Sollte beispielsweise dein Lieblingscasino keinen Bonus ohne Einzahlung anbieten, bedeutet das nicht automatisch, dass du beim falschen Casino gelandet bist. Um ein Casino kennenzulernen und mit niedrigen Einsätzen zu spielen, ist der Slot allerdings perfekt.
References:
https://online-spielhallen.de/lemon-casino-deutschland-eine-insider-analyse-aus-spielersicht/
Unsere Mission ist es, unseren Lesern stets akkurate Informationen zu Casinos und ihren Bonusangeboten zu liefern! Sie können entweder eine Auszahlung veranlassen oder einfach weiter spielen. Sobald Sie die Umsatzbedingungen erfüllt haben, sind Ihre verbleibenden Bonusgewinne auszahlbar. Gewinne auszahlen lassen oder weiterspielen Umsatzbedingung – Sie geben an, wie oft du den Betrag spielen musst, bevor du dir die Gewinne auszahlen lassen kannst.
Achten Sie gezielt auf No Deposit Angebote mit fairen Umsatzbedingungen (z. B. 20x statt 50x). Im Live-Casino warten klassische Tischspiele wie Roulette, Blackjack, Baccarat und Poker in zahlreichen internationalen Varianten auf Sie. Sie sind auch meist die erste Wahl, wenn es um Freispiele oder Bonusguthaben geht. Während Freispiele oft auf bestimmte Slots beschränkt sind, lässt sich Bonusguthaben flexibler auf viele Casino-Titel anwenden. No Deposit Boni können meist bei einer Vielzahl von Spielen eingesetzt werden – von Spielautomaten über Tischspiele bis hin zu Jackpot-Games.
References:
https://online-spielhallen.de/casino-venlo-cashback-ihr-umfassender-leitfaden/
kewadin casino st ignace
References:
https://empleos.contatech.org/employer/online-casino-geburtstagsbonus-2025-boni-und-freispiele/
Juli 2021 das Online-Glücksspiel in allen deutschen Bundesländern. Es ist schwer, die Lieblingsspiele zu finden, die auch Ihnen gefallen könnten. Möchten Sie die besten deutschen Online Casinos auf einen Blick vergleichen und sich bei dem vertrauenswürdigen Casino anmelden, das sich für Sie persönlich am besten eignet?
Es gibt so viele erstklassige Online-Casinos für Deutschland im 2025 und hier bei Top10Casinos.de ist es unsere Mission, es Ihnen leichter zu machen, die besten Seiten zum Spielen zu finden. Gemäß den aktuellen gesetzlichen Regelungen dürfen ausschließlich Anbieter mit einer gültigen GGL-Lizenz ihre Dienste in Deutschland legal anbieten. Diese Kriterien bestätigen dir die Sicherheit des Online Glücksspielanbieters. Seriöse Online Casinos bieten vor allem eine gültige Lizenzierung und transparente Richtlinien im Bezug auf Datensicherheit und Auszahlungsquoten.
References:
https://online-spielhallen.de/beste-online-casinos-deutschland-top-10-nov-2025/
Gave 199winbet4 a spin, and it’s alright! Nothing crazy, but a solid, reliable option. Good enough to kill some time and maybe win a few bucks. Take a peek at 199winbet4.
https://t.me/kazino_s_minimalnym_depozitom/19
Alright, 850bet1 isn’t bad. Games are what you’d expect, and I had a few wins. Worth a shot if you’re looking to try something different. Take a punt with 850bet1 maybe you can get lucky!
MBMBetapk, eh? Never heard of it, but I’m always down to try something new. Hopefully, it hits the spot! Check it out here: mbmbetapk
您將看到乘數符號隨機掉落在捲軸上。當您透過捲軸上的乘數符號獲得勝利時,總乘數將乘以您的總勝利,然後您將獲得最終值。 「奧林匹斯之門1000」的畫面和音效相輔相成,不僅展現古希臘神話的壯麗,也通過生動的動畫特效和激昂的音樂強化了遊戲的沉浸式體驗,不論是視覺還是聽覺都能讓玩家感受到神話世界的震撼。 「奧林匹斯之門1000」的畫面和音效相輔相成,不僅展現古希臘神話的壯麗,也通過生動的動畫特效和激昂的音樂強化了遊戲的沉浸式體驗,不論是視覺還是聽覺都能讓玩家感受到神話世界的震撼。 2026奧林匹斯之門的賠率設計合理,符號組合與特殊獎勵提供多樣化收益。從低額穩定獎勵到高額神祇獎金,每位玩家都能找到適合的遊玩節奏。UG Online 平台透明顯示符號賠率與中獎規則,幫助玩家掌握遊戲規律,提升策略性與遊戲樂趣。
http://www.boat7.com/1639/%ef%bc%9apragmatic-play/
下載 Olympus gates Deffend APKOlympus gates Deffend的官方開發商為Joystick-Games,雷電模擬器只提供應用程式Apk下載服務。 【我要重新搜尋】 The Secret of Secrets Gate of Olympus 可說是實至名歸的歐亞市場通吃,兩邊都很熱門的遊戲,甚至亞洲還出了不少”致敬遊戲”、以及致敬”致敬遊戲”的遊戲。 Gates of Olympus 1000 骰子遊戲提供高達15,000 倍投注額的贏利。 RTP高達96.50% ,相當不錯。這是一款高波動性老虎機遊戲,您可能需要等待一段時間才能贏取獎金,但一旦中獎,就能帶來豐厚回報。中獎頻率為 3.52 分之一,免費旋轉的中獎頻率為 448 分之一,這意味著免費旋轉需要很長時間才能觸發。最高中獎機率為 2,749,771 分之一。
However, some Dress to Impress codes give you exclusive outfits that are limited to events. You must redeem the codes before the developers expire them. SWEETHEART and WINTERUPDATE are some of the exclusive outfit codes for DTI that are now expired. We also look at the company behind the product to ensure it has an excellent reputation, independent casinos come with other remarkable benefits. All financial transactions can be carried out wherever you are so that you can enjoy your favourite titles as long as you have a stable internet connection, thinking this is the year. Roulette wheel american users reaching the highest level receive exceptional gifts as well as VIP support, some fruits. Be sure to bookmark this page so you can come back for more codes as they are updated. If you’re looking for codes or free items for your Avatar, then make sure to check out our Roblox Promo Codes page!
https://pandora178.net/15-dragon-pearls-by-3-oaks-an-exciting-casino-game-review-for-aussies/
Dogecoin Online Gambling Affiliate program If slot providers were people, Pragmatic Play would be that hyper-caffeinated maniac who builds a new game every five minutes, wins trophies in their sleep, and still shows up to every party with fireworks and a fistful of jackpots. No matter if you are brand new to online casino games or a seasoned player, we believe there are many benefits of playing casino games for free in demo mode. In addition to the obvious entertainment aspect, you can take advantage of benefits including the following: If you like strategic challenges, our range of strategic dice games is designed especially for you. Test your skills, devise winning strategies and outsmart your opponents in games that combine luck and strategy – the perfect combination. Mega Wheels by Air Dice, one of the most popular games at our online casino for a long time now, is an example of this type of game.
You receive no deposit free spins for simply joining the casino, or Friday. The best online casinos to play gates of olympus we understand what youre looking for, 27 July. It’s great to have some bonus plays on the slots as a perk of being a new customer. All of this amounts to a generous welcome package. Private wireless networks and industrial edge are the keystone for the digitalization of industries, connecting workers and machines to increase safety, productivity and efficiency. Thematically, Gates of Olympus will appeal to more players than Sweet Bonanza. The RTP rate is 96.5% is marginally higher too. That said, Sweet Bonanza offers maximum wins of 21,175 times your total bet whilst the Greek mythology version has top payouts of 5,000 times your total bet. You are more likely to achieve the max wins in Gates of Olympus though due to the higher multipliers in the base game and free spins.
https://fishermancharters.ca/why-tikitaka-casino-is-a-top-choice-for-uk-players/
© 2023 WebWarrior. All rights reserved. To celebrate the launch of this innovative release, Booongo is offering a 15 Dragon Pearls: Release tournament. From now through September 4, players can take part in the event. There is a total of €30,000 in prize money on offer. A unique wine tasting and painting experience that combines creativity, wine learning and a friendly competition between Australian and New Zealand wines. Introduction In a world awash with content, a consistent brand voice is your beacon—it guides how your audience perceives you, A unique wine tasting and painting experience that combines creativity, wine learning and a friendly competition between Australian and New Zealand wines. Why choose a casino without registration? You can chat with other players and even tip the dealer after a big win, win real money slot machines there are amazing features they bring that are priceless. Slot hyper karts by light and wonder demo free play most of the common questions are answered in detail here and more are being added, we add it to the welcome bonus list. As for the actual game, released in 2023 by Belatra Games.
Welcome to the exciting underwater world of Big Bass Splash, the fifth instalment in Pragmatic Play’s celebrated Big Bass series. Big Bass Bonanza is a popular video slot brought to you by the creative team at Pragmatic Play. It’s a game that’s part of Pragmatic’s unique Drops & Wins promotion, and players can choose whether to opt-in when the slot loads. Rich Wilde is synonymous with big wins and ancient riches, and you can join the famed explorer on his adventures around Egypt through the Book of Dead slot. Highly volatile, Book of Dead offers ample opportunities for big wins, ideal for braver slot game enthusiasts. Big Bass Bonanza Megaways \n The Biggest Football Festival of Summer 2024\n \n \n \n
https://beting88.com/diepgaande-review-van-1xbet-casino-voor-spelers-uit-nederland/
Big Bass Splash Rund 47,6% der Handy-Nutzer in der Schweiz haben ein iPhone laut Umfrage von 2023. Aufgrund der Beliebtheit von iOS-Geräten achten wir bei unseren Tests darauf, dass Sie die App direkt im Apple AppStore herunterladen oder ohne Probleme per Instant Play im nativen Safari Browser spielen können. dieses Big bass splash ist für mich einfach nur ein betrug an den kunden. Da werden events versprochen die nicht eingehalten werden. Het leuke aan spelen bij JACKS.NL is dat er altijd wel casino promoties te ontdekken zijn waar je van kunt profiteren. Natuurlijk is er onze online casino welkomstbonus, maar op ieder moment kun je als geregistreerde speler genieten van een casino promotie. Maar waarom zou je profiteren van de casino promoties van JACKS.NL? Simpel: omdat deze acties je duizenden tot tienduizenden euro’s aan bonusgeld op kunnen leveren, omdat onze Free Spins specials je een flink aantal gratis spins voor online gokkasten op kunnen leveren, omdat je extra’s voor tafelspellen zoals roulette en blackjack kunt pakken en omdat je Free Bets en Profit Boosts voor sportweddenschappen kunt winnen. Hebben we je overtuigd?
Offline games often use virtual credits — bet smaller to extend your session and maximize fun. The Gates of Olympus app features: Are there any similar casino games like Gates of Olympus? Cari jawaban cepat untuk pertanyaan terpopuler How do I download the Gates of Olympus app to my phone? The Gates of Olympus app features: Monitoring Real-time Tingkat Pengembalian Slot Terpopuler For Gates fans, Gates of Olympus Super Scatter is the gift that keeps on giving, and since the RTP is about the same, the gameplay is about the same, yet winning potential is through the roof, picking this one over the original makes a whole lot of sense, as it breathes a big gust of wind into the series in the process.. SLOT777 adalah platform slot gacor 777 terbaru yang mengundang Anda untuk menikmati permainan dari beragam provider terbaik (seperti Pragmatic, PG Soft, dan Habanero) dengan RTP yang terbukti mencapai 98%. Untuk memastikan pengalaman online yang GACOR, RESPONSIF, DAN ANTI RIBET, SLOT777 dari COY99 menyediakan APK yang sudah terverifikasi aman serta 5 opsi deposit paling populer di Indonesia. Anda dapat dengan mudah melakukan deposit melalui transfer antar bank (BCA, BNI, MANDIRI), Virtual Account (Gopay, Dana, OVO), Pulsa (Telkomsel, XL), hingga mata uang crypto (USDT, IDRT). Seluruh kemudahan dan keamanan bermain ini dijamin oleh lisensi resmi dari PAGCOR serta AGI di Indonesia.
https://nammaooruglobalschools.in/raging-bull-casino-game-review-experience-the-thrill-in-australia/
Take a look at the slot metrics to see if that’s the greatest choice for you. Dragon Pearls: Hold & Win offers 95.01% return, Average volatility and x1000 win potential, max win. With a quite balanced math model and the possibility of the massive swings, the game is always exciting. Overall, it delivers powerful gaming experience. Trung Le Nguyen. Random House Graphic, $24.99 hardcover (224p) ISBN 978-1-9848-9267-6; $17.99 paper ISBN 978-1-9848-9266-9. Ages 12 and up. Nguyen spins a captivating tale of romance, grief, and community in a graphic novel that draws inspiration from “East of the Sun and West of the Moon” and Cyrano de Bergerac. See our q&a with Nguyen. The book received a starred review from PW. —Anonymous, 41, Texas The above-mentioned online casinos are some of the best in the country, you will find ZenCasino as a perfect partner online. The sunset is the wild symbol of the Raging Rhino Ultra online slot, which indicate the amount of money returned to players over time. Pokies city casino once you get into the game, and players can see the results as they happen. The popularity of online pokies can be attributed to many factors, it has become easier than ever to place bets on your favorite sports.
This website is using a security service to protect itself from online attacks. The action you just performed triggered the security solution. There are several actions that could trigger this block including submitting a certain word or phrase, a SQL command or malformed data. This website is using a security service to protect itself from online attacks. The action you just performed triggered the security solution. There are several actions that could trigger this block including submitting a certain word or phrase, a SQL command or malformed data. This website is using a security service to protect itself from online attacks. The action you just performed triggered the security solution. There are several actions that could trigger this block including submitting a certain word or phrase, a SQL command or malformed data.
https://villageflix.com/2025/12/23/instant-casino-en-grundig-anmeldelse-for-norske-spillere/
Gates of Olympus tar deg med på en mytologisk reise til antikkens Hellas, der du møter selveste Zevs på Olympus-fjellet. Jeg har selv tatt turen for å sjekke hva som er så spesielt med dette gudommelige fjellet. Les anmeldelsen min og bli med til antikkens Hellas du også. Høydepunktet på Gates of Olympus er en saftig bonusrunde med free spins, men vi skal heller ikke glemme å nevne multiplikatorsymbolene, som dukker opp både der og i hovedspillet. Mobilversjonene av Gate of Olympus gir spillere den samme opplevelsen som på PC, men med fleksibilitet til å spille hvor som helst. Spillmotoren er optimalisert for berøringsskjermer, slik at symbolene reagerer presist på hver bevegelse. Grafikken er gjengitt i full HD, og tumbling-funksjonen flyter jevnt selv på enheter med lavere ytelse. Demoversjonen, gate of olympus demo, kan også startes direkte i appen uten registrering, noe som lar spilleren teste multiplikatorer, gratisspinn og tempo før man går over til ekte spill. Alle funksjoner, inkludert lydspor, animasjoner og bonusrunder, er identiske med desktop-utgaven.
Run an evaluation A few. I wouldn’t call it many. Remember: Players, coaches and staff already know what’s happening around the team. Their need to read and watch what people say in a forum such as this isn’t overly high. Currently, there are 12 games, such as Bandi, which is aimed at absolute beginners and teaches the basics necessary to play the other games. There's also: GO Copyright © 2025 Vortex Competitions. per pipeline run If you are modding a Steam game, you need to configure Steam to run BepInEx The Gen AI evaluation service in Vertex AI lets you evaluate any generative model or application and benchmark the evaluation results against your own judgment, using your own evaluation criteria. Evaluating Gen AI is integrated within Vertex AI to help you launch and reuse evaluations as needed.
https://www.terabytelytics.com/aviator-pakistan-game-what-to-expect/
The game is known for its high volatility, meaning players can experience both dry spells and massive payouts. With its eye-catching graphics, fun soundtrack, and rewarding bonus features, Sugar Rush 1000 is a must-try for slot enthusiasts looking for a sugar rush of excitement. Connect with us Sugar Rush 1000 takes the original game and stacks it with so much sugary goodness it’s almost too much of a good thing. We offer the most popular games at the click of a button, providing an authentic casino experience from the comfort of your home. And thanks to our excellent offering of games, such as online Slots, our dedicated customer support team and our range of responsible gaming tools, we’re the destination for players from around the world. Untuk bantuan silakan,Klik disini Usually, the visuals in these upgrade slots don’t change a lot, and so it is in Sugar Rush 1000. Players are treated to the same sort of pinky, pastely, fluffy candy world where inhabitants are able to chow down on just about everything they see. The same cheerfully amateurish-looking symbols line the gaming grid; the same feel-good factor is here, so returning gamblers should instantly feel at home when sinking their teeth into Sugar Rush 1000.
Gates of Olympus 1000 destaca por un estilo muy característico y, además, la posibilidad de crear combinaciones ganadoras en cualquier posición de los carretes resulta muy atractiva. Sin embargo, antes de que pases a la acción, te recomendamos que pruebes la tragamonedas en modo demo. Al igual que el título original, Gates of Olympus, Gates of Olympus 1000 viene con un RTP del 96,5%. También tiene una alta volatilidad, lo que da la posibilidad de conseguir algunas ganancias impresionantes. Por supuesto, la alta volatilidad también significa que las ganancias pueden no ser frecuentes pero, en general, vale la pena esperar. COPYRIGHT © 2015 – 2025. Todos los derechos reservados a Pragmatic Play, una sociedad de inversión de Veridian (Gibraltar) Limited. Todos y cada uno de los contenidos incluidos en este sitio web o incorporados por referencia están protegidos por las leyes internacionales de derechos de autor.
http://www.babelcube.com/user/natalie-campbell-1
BC.Game está en nuestra lista de sitios web de apuestas con BTC debido a la flexibilidad del servicio de este operador. Es uno de los pocos que ofrece una casa de apuestas deportivas, casino en línea y lotería en línea en la misma plataforma. Cargar cualquiera de las tres pestañas toma segundos, ¡y desde ahí, comienza el juego! BC.Game tiene mucho que ofrecer a los fanáticos de los juegos de casino. Tiene juegos originales, mesas con crupieres en vivo y una serie de jackpots. Un buen detalle es que tienen una sección para juegos de alta volatilidad. Betpanda.io shines for its crypto-friendly bonus offerings, making it an attractive destination for new and experienced players alike. New users can claim a 100% matched deposit bonus up to 1 BTC, giving a strong start to explore the casino’s vast library of over 5,000 games. This bonus allows players to test popular slots like Gates of Olympus, Sweet Bonanza, and Dead Canary, or enjoy live dealer and table games without risking too much of their own funds.
€3,99 incl. BTW Features zijn er ook in Sugar Rush en daar hebben we gelukkig genoeg over te vertellen. Zo kun je je opmaken voor de volgende Sugar Rush features. Sugar Rush is een alleraardigste online gokkast van Pragmatic Play. Het is geen hele diepgaande gokkast, maar dat hoeft ook niet altijd. De bonusspelletjes vallen vaak en vooral de taartenbonus is erg leuk. 12.500+ tevreden Label Kiki-ladies Hartelijk dank voor je feedback. Dit product is niet beschikbaar. Kies een andere combinatie. Aanvraag voor: Scheepjes Maxi Sugar Rush – 398 colonial rose – Katoen Garen Sugar Rush is een videoslot van Pragmatic Play wat betekent dat er een hoop spellen van deze maker in casino’s te vinden is. De gokkasten van Pragmatic Play zijn al volop te vinden bij de beste online casino’s die we op onze website aanraden. Op de website van CasinoRaadgever vind je de beste online casino’s om Sugar Rush zelf te spelen. Veel van deze casino’s bieden ook online casino bonussen aan dus je doet er goed aan hier gebruik van te maken zodat je het meeste uit je eerste spins haalt.
https://dados.uff.br/ne/user/vesflowsana1973
Money Vault – Maak kans op extra cashprijzen tijdens het spelen. Money Controls table game play at no cost otherwise real cash Leo Vegas slot games today Read More » LCB.org gebruikt cookies om er zeker van te zijn dat je deze website zo goed mogelijk beleeft. Meer informatie ● Weddenschappen die worden geplaatst op spelers die niet deelnemen,worden ongeldig verklaard.● Tenzij anders vermeld tellen verlenging en penalty-shoot-outs niet mee.● De verwerking van markten zal worden bepaald aan de hand van OPTA-gegevens.● Wijzigingen in OPTA-gegevens na het laatste fluitsignaal worden genegeerd. Bekijk hier de 893 casinos casino’s die afgeleid uit 54622 stemmen van onze leden een gemiddelde score hebben gekregen van 2.9 uit 5. Afgeleid uit 1003 stemmen, hebben onze leden een score gegeven van 2.9 aan de 100 spellen gokkasten die we bij LCB hebben gerecenseerd.
В мире азарта, где всякий ресурс стремится заманить заверениями простых призов, рейтинг казино честных
становится как раз той путеводителем, что направляет сквозь ловушки рисков. Игрокам профи да начинающих, что устал из-за ложных обещаний, он инструмент, чтобы ощутить реальную отдачу, как ощущение золотой монеты на пальцах. Без ненужной воды, лишь реальные клубы, где отдача не лишь число, а конкретная удача.Подобрано из яндексовых трендов, как паутина, что вылавливает наиболее свежие тенденции на рунете. Тут отсутствует пространства про клише фишек, любой момент словно ход у покере, там блеф проявляется сразу. Игроки понимают: по стране стиль речи и подтекстом, там юмор притворяется как рекомендацию, помогает избежать рисков.На https://www.don8play.ru/ этот топ ждёт будто готовая раздача, готовый на игре. Зайди, если нужно почувствовать пульс подлинной ставки, минуя иллюзий да провалов. Тем кто любит ощущение приза, он словно взять ставку у ладонях, минуя глядеть в экран.
**mitolyn**
Mitolyn is a carefully developed, plant-based formula created to help support metabolic efficiency and encourage healthy, lasting weight management.